Key Takeaways
- US online casino revenue grew 12% year over year in the third quarter of 2026, the slowest growth rate on record, according to Citizens Equity Research.
- FanDuel, DraftKings and BetMGM remain the three largest online casino operators, but all lost market share compared with the same quarter last year.
- Fanatics, BetRivers and bet365 gained market share as competition intensified across the regulated US online casino industry.
The US online casino industry is still growing, but its expansion has slowed considerably. New research from Citizens Equity Research shows that online casino revenue increased 12% year over year during the third quarter of 2026, marking the slowest growth rate recorded by the firm.
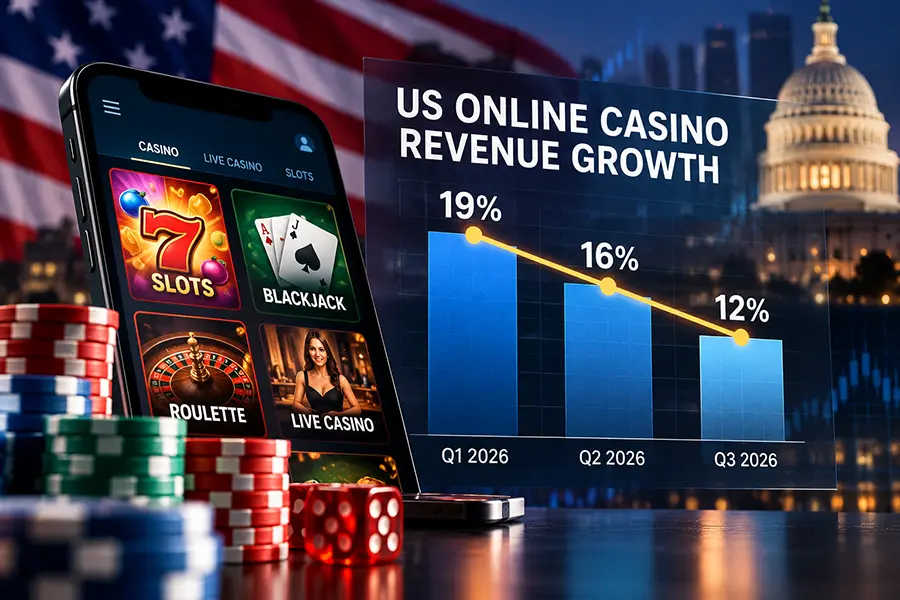
The slowdown follows a stronger start to the year, when online casino revenue grew 19% in the first quarter and 16% in the second quarter. Although revenue continues to increase, the latest figures suggest that the rapid growth experienced by the regulated online casino market is beginning to moderate.
The report, released October 27, also reveals changes in the competitive landscape. FanDuel, DraftKings and BetMGM remain the industry’s dominant operators, but each lost market share compared with the third quarter of 2025.
Meanwhile, smaller competitors, including Fanatics, BetRivers and bet365, gained ground.
US Online Casino Revenue Growth Falls to 12%
According to Citizens Equity Research, online casino revenue increased 12% during the three months ending September 30, 2026, compared with the same period last year.
That represents a noticeable decline from the growth rates recorded earlier in 2026.
| Period | Year-over-Year Revenue Growth |
|---|---|
| Q1 2026 | 19% |
| Q2 2026 | 16% |
| Q3 2026 | 12% |
The slowdown was largely in line with analysts’ expectations, suggesting that the industry had already been preparing for more moderate growth.
Monthly results also showed some stabilization toward the end of the quarter. Online casino revenue growth reached 11% in August before improving slightly to 12% in September.
These figures do not mean Americans are spending less money at online casinos overall. Revenue is still increasing compared with last year, just at a slower pace.
That distinction matters because slowing growth and declining revenue are two different things.
A market growing 12% annually remains an expanding industry. However, operators accustomed to faster growth may face greater pressure to attract new customers and retain existing players.
FanDuel Remains the Largest US Online Casino Operator
FanDuel retained its position as the largest operator in the regulated US online casino market, although its market share continued to decline.
The company controlled 25.1% of the market during the third quarter, down from 26.6% during the same period in 2025.
FanDuel has now experienced a decline in online casino market share in each of the first three quarters of 2026.
DraftKings remained in second place with 22.2%, compared with 24.3% a year earlier.
BetMGM ranked third at 18.6%, down from 20.7%.
Together, the three operators accounted for approximately 66% of the market, demonstrating how concentrated the regulated US online casino industry remains.
However, their combined share declined from approximately 72% a year earlier.
That change suggests that smaller competitors are gradually capturing a larger portion of the market, even though the established leaders continue to dominate.
US Online Casino Market Share: Q3 2025 vs. Q3 2026
The Citizens research highlights how the market changed over the past year.
| Operator | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| FanDuel | 26.6% | 25.1% | -1.5 pts |
| DraftKings | 24.3% | 22.2% | -2.1 pts |
| BetMGM | 20.7% | 18.6% | -2.1 pts |
| BetRivers | 6.8% | 7.4% | +0.6 pts |
| Caesars | 7.1% | 6.4% | -0.7 pts |
| Fanatics | 3.9% | 5.2% | +1.3 pts |
| bet365 | 0.4% | 1.7% | +1.3 pts |
Source: Citizens Equity Research, as reported by NEXT.io. Figures represent the regulated US online casino market covered by the research, not offshore casinos or sweepstakes platforms.
The most significant declines came from DraftKings and BetMGM, which each lost 2.1 percentage points compared with the previous year.
Fanatics and bet365 recorded the largest percentage-point gains among the operators listed.
Market share measures an operator’s portion of total industry revenue. A declining share does not necessarily mean a company generated less revenue than the previous year, particularly when the overall market is still expanding.
DraftKings Shows Signs of Recovery Despite Annual Decline
Although DraftKings lost market share compared with 2025, its quarterly performance showed signs of improvement.
The company’s share increased from 20.9% in the second quarter to 22.2% in the third quarter.
According to Citizens, this was DraftKings’ first consecutive-quarter market share improvement in approximately two years.
Analysts suggested that adjustments to the company’s business model earlier in 2026 may have contributed to the recovery.
The improvement is notable because DraftKings has faced sustained competition from FanDuel and BetMGM, along with newer operators attempting to establish themselves in regulated online casino states.
However, one quarter of improvement does not establish a lasting turnaround.
DraftKings remains below its market share from a year earlier, and future results will determine whether its recent gains can be sustained.
BetMGM Records Sixth Consecutive Quarterly Decline
BetMGM experienced another difficult quarter in terms of market share.
Its portion of the US online casino market fell to 18.6%, compared with 20.7% during the third quarter of 2025.
According to Citizens, the result marked BetMGM’s sixth consecutive quarterly decline in market share.
The company remains one of the largest online casino operators in the country, but its position has weakened as competing platforms expand.
BetMGM’s decline also illustrates how difficult it can be for established operators to maintain their share of an increasingly competitive market.
A recognizable brand and an established customer base do not guarantee that an operator will continue capturing the same percentage of industry revenue.
However, the Citizens figures alone do not explain whether BetMGM’s declining share resulted from changes in promotional spending, customer behavior, game selection or other competitive factors.
Fanatics, BetRivers and bet365 Gain Ground
While the industry’s largest operators lost market share, several competitors reported meaningful gains.
Fanatics increased its share from 3.9% to 5.2%, one of the largest improvements recorded during the quarter.
The company remained slightly below its second-quarter share of 5.4%, but its annual growth demonstrates that it has established a larger presence in the online casino market.
BetRivers, operated by Rush Street Interactive, also improved its position. Its share increased from 6.8% to 7.4%.
Bet365 experienced particularly strong growth, increasing its share from 0.4% to 1.7%.
Its expansion into Michigan and West Virginia helped support those gains.
Citizens noted that the initial growth benefits associated with newer market launches by bet365 and Hard Rock were beginning to moderate.
That is an important distinction. Launching in additional states can provide a significant initial increase in revenue, but sustaining that growth becomes more challenging once the launch period passes.
For smaller operators, the longer-term challenge is retaining customers and expanding their share without relying exclusively on new market entries.
Why Is US Online Casino Growth Slowing?
The Citizens report confirms that growth has slowed, but it does not establish one definitive cause.
Several broader industry factors help explain why maintaining rapid expansion can become more difficult as a market develops.
One is the limited number of states that currently permit regulated real-money online casinos.
Unlike online sports betting, which is available in many more states, licensed real money online casinos remain restricted to a relatively small number of jurisdictions.
That limits the industry’s ability to expand geographically.
Another factor is competition within existing markets.
Major operators already have established customer bases in states such as New Jersey, Pennsylvania and Michigan. As those markets develop, attracting additional customers can become more difficult than during their initial expansion.
New competitors can also redistribute revenue without necessarily creating equivalent growth for the overall market.
For example, a player switching from one licensed casino to another changes the operators’ respective market shares but does not automatically increase total industry spending.
These factors provide useful context for the slowdown, although the available research does not quantify how much each contributed to the third-quarter result.
Sports Betting Holds Steady While Online Casino Growth Cools
The Citizens report also examined the US sports betting industry, which performed more consistently during the quarter.
Sports betting handle, representing the total amount wagered, increased 7% year over year.
That growth occurred despite the quarter containing one fewer week of NFL games than the comparable period in 2025.
Industry-wide sportsbook gross gaming margin remained at 9.6%.
DraftKings retained the largest share of sports betting handle at 37.6%, followed by FanDuel at 32.8%.
The findings suggest that online sports betting and online casinos are experiencing different competitive conditions.
Sports betting continues to benefit from a broader geographic footprint and major sporting events, while online casino growth remains more dependent on activity within a smaller group of regulated states.
Citizens analyst Jordan Bender has also argued that prediction markets have not yet demonstrated a major negative impact on licensed sportsbook activity.
That assessment remains subject to change as prediction markets expand and more operating data becomes available.
What Does Slower Growth Mean for Online Casino Players?
For players, the immediate impact of slower industry growth is less clear than the financial implications for operators.
The market share figures show that customers are generating a larger portion of industry revenue at certain casino brands and a smaller portion at others.
They do not establish whether individual players are receiving better bonuses, faster withdrawals or improved gaming experiences.
However, the growing presence of operators such as Fanatics, BetRivers and bet365 means customers in states with multiple licensed casinos may have more established brands to compare.
Competition can create incentives for operators to improve their products, but it does not guarantee better promotions or more favorable terms.
Players should continue comparing online casino reviews and evaluating operators based on licensing, withdrawal policies, payment methods, bonus wagering requirements and responsible gambling protections rather than market share alone.
The figures also apply to the regulated US online casino market. They should not be treated as a measure of the offshore casino industry, which operates under different licensing arrangements and does not have comparable comprehensive public revenue reporting.
What Comes Next for the US Online Casino Industry?
The third-quarter results show an industry entering a more competitive stage of development.
US online casino revenue is still increasing, but growth has slowed from 19% at the beginning of the year to 12% in the latest quarter.
FanDuel, DraftKings and BetMGM continue to control most of the market, although their combined share is shrinking.
Meanwhile, Fanatics, BetRivers and bet365 are demonstrating that smaller competitors can gain ground against established operators.
The next several quarters will help determine whether the slowdown represents a temporary period of moderation or a longer-term shift toward more modest industry
Last Updated: 1 hour ago


